Suppose a shop pays THB 30,000 today and receives THB 12,000 a year for the next three years. The receipts add up to THB 36,000. Is that enough to decide whether the investment is worthwhile? Keep that question for the final exercise. Along the way, you’ll put cash flows on a timeline, measure risk, and calculate a discount rate using the cost of capital.
This guide follows the four GA514 classes. The examples and exercises use hypothetical figures. Enter rates as decimals. Round your answers at the end, except in the loan schedule, where each month’s amounts are rounded to the nearest satang.
1. The financial environment
A business has to decide what to invest in, how to raise the money, and how much cash it needs to pay its bills on time. If a shop makes THB 100,000 in credit sales and collects THB 60,000, its cash receipts from those sales for the period are THB 60,000. The other THB 40,000 remains in accounts receivable. If it pays suppliers and employees THB 50,000 during the same period, these transactions generate THB 10,000 in net cash.
Free cash flow to the firm (FCF in this guide) is cash from operations after operating taxes and investment in assets and working capital, before payments to lenders and shareholders. One way to value a business is to forecast its future FCF and discount it at a cost of capital appropriate to its risk.
A business’s legal form affects how it raises money and the liability its owners may face. A sole proprietorship has one owner, a partnership has partners, and a corporation can divide ownership into shares. Lenders have contractual rights. Common shareholders have a claim on what remains after obligations are paid. Derivatives take their value from another price or rate. A currency forward, for instance, can lock in what a future payment will cost in baht.
| What question are you asking? | Market categories |
|---|---|
| When is delivery due? | Spot markets for near-immediate delivery and forward markets for future delivery |
| What is the instrument’s maturity? | Money markets for short-term debt, generally up to one year, and capital markets for stocks and longer-term debt |
| Who sells the security? | Primary markets when issuers sell new securities and secondary markets when investors trade existing securities |
A nominal debt yield reflects the real risk-free rate and premiums for factors such as inflation, default, liquidity, and maturity. Cross-border transactions also carry country risk, such as restrictions on transferring money, and exchange-rate risk.
Exercise 1. A company sells a new five-year bond to an investor. The investor sells the same bond to a friend a year later. Identify the market and who receives the proceeds in each transaction. The company also owes a foreign supplier USD 1,000 in three months and locks in an exchange rate of THB 35 per dollar. How much should it budget, assuming zero fees?
Answer to exercise 1
The first sale takes place in the primary market and the company receives the proceeds. The second takes place in the secondary market and the selling investor receives the proceeds. Both are capital market transactions. The company budgets 1,000 × 35 = THB 35,000 for the supplier payment.
2. The time value of money
At 8% compounded annually, THB 10,000 today has a future value (FV) of 10,000 × 1.08² = THB 11,664 at the end of two years. To find the present value (PV) of THB 11,664 received at the end of year two, reverse the calculation with 11,664 ÷ 1.08² = THB 10,000. The general formulas are FV = PV × (1+i)ⁿ and PV = FV ÷ (1+i)ⁿ, where i is the rate per period and n is the number of periods.
Receiving THB 2,000 at the end of each of years 1, 2, and 3 at a 5% annual rate is an ordinary annuity.
- The value at the end of year 3 is 2,000 × (1.05² + 1.05 + 1) = THB 6,305.00.
- The value today is 2,000 ÷ 1.05 + 2,000 ÷ 1.05² + 2,000 ÷ 1.05³ = THB 5,446.50.
- Payments at the start of years 1, 2, and 3 each arrive one period earlier, making this an annuity due. For the same valuation dates, multiply the ordinary annuity values by 1.05. FV is THB 6,620.25 and PV is THB 5,718.82.
The shortcuts for an ordinary annuity are FV = PMT × ((1+i)ⁿ−1) ÷ i and PV = PMT × (1−(1+i)⁻ⁿ) ÷ i, where PMT is the payment per period. At i = 0, both reduce to PMT × n. For unequal payments, move each cash flow to the same date before adding them.
When the rate is annual and payments are monthly
A quoted annual rate of 12% compounded monthly gives a rate of 1% per month and an effective annual rate (EAR) of (1.01)¹²−1 ≈ 12.68%. For a nominal annual rate j compounded m times per year, the periodic rate is j ÷ m and EAR = (1+j/m)ᵐ−1. To compare offers with different compounding frequencies, convert both to EAR and account for fees as well.
Take a THB 12,000 loan repaid in three end-of-month installments at 1% per month. Rearrange the annuity PV formula to get a payment of 12,000 × 0.01 ÷ (1−1.01⁻³) ≈ THB 4,080.27.
| Month | Opening principal | Interest | Principal repaid | Closing balance |
|---|---|---|---|---|
| 1 | 12,000.00 | 120.00 | 3,960.27 | 8,039.73 |
| 2 | 8,039.73 | 80.40 | 3,999.87 | 4,039.86 |
| 3 | 4,039.86 | 40.40 | 4,039.86 | 0.00 |
Calculate each month’s interest on the opening balance. The first two payments are THB 4,080.27. The final payment is THB 4,080.26 to clear the balance after rounding to satang.
Exercise 2. A customer offers THB 11,000 in six months or THB 10,500 today. The comparison rate is 1% per month and both options have the same risk. Which payment would you take?
Answer to exercise 2
11,000 ÷ 1.01⁶ ≈ THB 10,362.50. THB 10,500 today is worth more when both offers are valued as of today.
3. Risk and return
Expected return is the probability-weighted average E(R) = Σ pᵢRᵢ. Standard deviation σ = √[Σ pᵢ(Rᵢ−E(R))²] measures how widely returns vary around their mean. The coefficient of variation CV = σ ÷ E(R) compares volatility per unit of expected return when the expected return is positive and sufficiently far from zero.
| Scenario | Probability | Return on A | Return on B | 50/50 portfolio |
|---|---|---|---|---|
| Weak | 25% | −4% | 8% | 2% |
| Normal | 50% | 8% | 6% | 7% |
| Strong | 25% | 20% | 4% | 12% |
A’s expected return is 0.25 × (−4%) + 0.50 × 8% + 0.25 × 20% = 8%. Its standard deviation is √[0.25 × (−12)² + 0.50 × 0² + 0.25 × 12²] ≈ 8.49 percentage points, giving a CV of about 1.06. B’s expected return is 6%. Using the portfolio return in each scenario gives the 50/50 portfolio an expected return of 7% and a standard deviation of about 3.54 percentage points.
In this example, A rises as B falls and their correlation is −1. Covariance shows whether returns tend to move together or in opposite directions. Correlation puts that relationship on a scale from −1 to 1. Estimating portfolio risk therefore requires the weights and how the assets move in relation to one another.
The efficient frontier contains portfolios with the highest expected return for a given level of risk or the lowest risk for a given expected return. When the model includes a risk-free asset, investors can adjust risk by changing the split between that asset and a risky portfolio.
Diversification reduces company-specific risk, such as a factory shutdown. Market-wide risk remains.
The capital asset pricing model (CAPM) uses beta (β) to measure how sensitive returns are to market movements. The required return is Rf + β × (Rm−Rf), where Rf is the risk-free rate and Rm−Rf is the market risk premium. Portfolio beta is the sum of each asset’s beta multiplied by its portfolio weight. Arbitrage pricing theory (APT) and Fama–French models use multiple common factors to explain returns.
Exercise 3. A portfolio holds 75% in A and 25% in B. For a separate benchmark calculation, assume betas of 1.2 for A and 0.4 for B. The risk-free rate is 2% and the market risk premium is 5%. Calculate the CAPM required return and compare it with the expected return from the table.
Answer to exercise 3
Portfolio beta = 0.75 × 1.2 + 0.25 × 0.4 = 1.0. The required return is 2% + 1.0 × 5% = 7%. Using the table as a separate return forecast gives 0.75 × 8% + 0.25 × 6% = 7.5%, or 0.5 percentage points above the assumed hurdle.
4. Weighted average cost of capital
The weighted average cost of capital (WACC) is the sum of each source’s cost multiplied by its weight. Use an appropriate target capital structure or market-value weights when no target is available. Estimate the cost of raising money today. Non-interest-bearing trade payables are generally excluded from the financing weights.
- When interest is deductible and the company can use the full tax benefit, the after-tax cost of debt is the pretax cost × (1−tax rate).
- For preferred stock paying a fixed dividend with no redemption date, divide the annual dividend by the share price.
- For common equity, use CAPM or D₁ ÷ P₀ + g when a constant long-run dividend growth rate is a reasonable assumption. D₁ is next period’s dividend, P₀ is today’s share price, and g is the growth rate. Another method adds an equity risk premium to the company’s debt yield. If new shares carry issuance costs, account for net proceeds when using the dividend-based method.
| Funding source | Market value (THB millions) | Weight | Cost used | Weight × cost |
|---|---|---|---|---|
| Debt | 3 | 30% | 6% × (1−20%) = 4.8% | 1.44% |
| Preferred stock | 1 | 10% | 8% | 0.80% |
| Common equity | 6 | 60% | 2% + 1.2 × 5% = 8% | 4.80% |
| Total | 10 | 100% | 7.04% |
Use the 7.04% WACC to discount FCF for a project with comparable risk and a financing structure consistent with the calculation. A project with different risk calls for a discount rate suited to that project.
Exercise 4. If the pretax cost of debt rises from 6% to 7% and the other inputs stay the same, what is the new WACC? How many percentage points did it rise?
Answer to exercise 4
The after-tax cost of debt is 7% × (1−20%) = 5.6%. Multiply by the 30% weight to get 1.68%. The new WACC is 1.68% + 0.80% + 4.80% = 7.28%, up 0.24 percentage points.
Review with one case
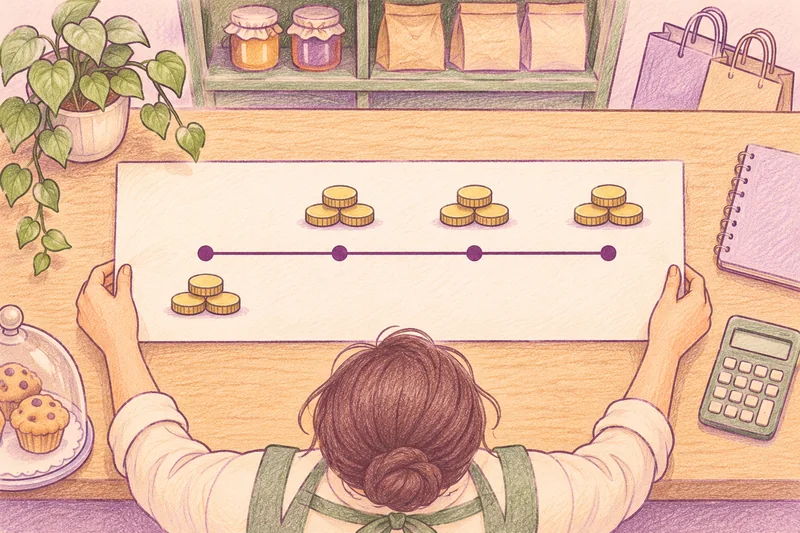
Return to the THB 30,000 project. Assume the THB 12,000 payments are year-end FCF for three years, the project’s risk and financing fit the WACC example, and there is no residual value. Use the timeline from section 2 and put −30,000 at t = 0 and +12,000 at t = 1, 2, and 3. Calculate net present value (NPV) at 7.04%. What happens if the last year’s cash flow falls to THB 9,000?
Answer to the review case
The present value of the three payments is about THB 31,468.79. Subtract the upfront investment for an NPV of about +THB 1,468.79. The project adds value under the first set of assumptions. If the last payment drops by THB 3,000, subtract 3,000 ÷ 1.0704³ ≈ THB 2,446.15 from the original NPV. The new NPV is about −THB 977.36.
Before you check your work, make sure each cash flow is in the right period, the rate matches the period, probabilities or weights add to 100%, and the discount rate fits the cash flow risk.
The finance concepts and topic sequence follow the GA514 Fundamentals of Business Finance course handout by Assoc. Prof. Wanrapee Banchuenvijit, PhD, CISA (2023). The examples, exercises, and illustrations were created for this guide.