Should we expand the team as soon as work grows?
A team takes on more jobs, but its manager spends more time in meetings. A factory buys another machine, yet orders come in waves and the machine sits idle. When we say the business is “growing,” we need to ask what is growing and what happens to cost per accepted deliverable.
Here I first separate adding people under an existing constraint from changing the scale of the whole business. Then I consider expansion, investment in reusable work, and buying an outside service. Every number is hypothetical, not a result from any company.
The long run does not begin after a fixed year
The short run is a period when some production inputs cannot yet change. In the long run, all inputs can be adjusted. One business may wait for a lease to end; another may change its process sooner. A fixed number of months cannot separate the two for everyone.
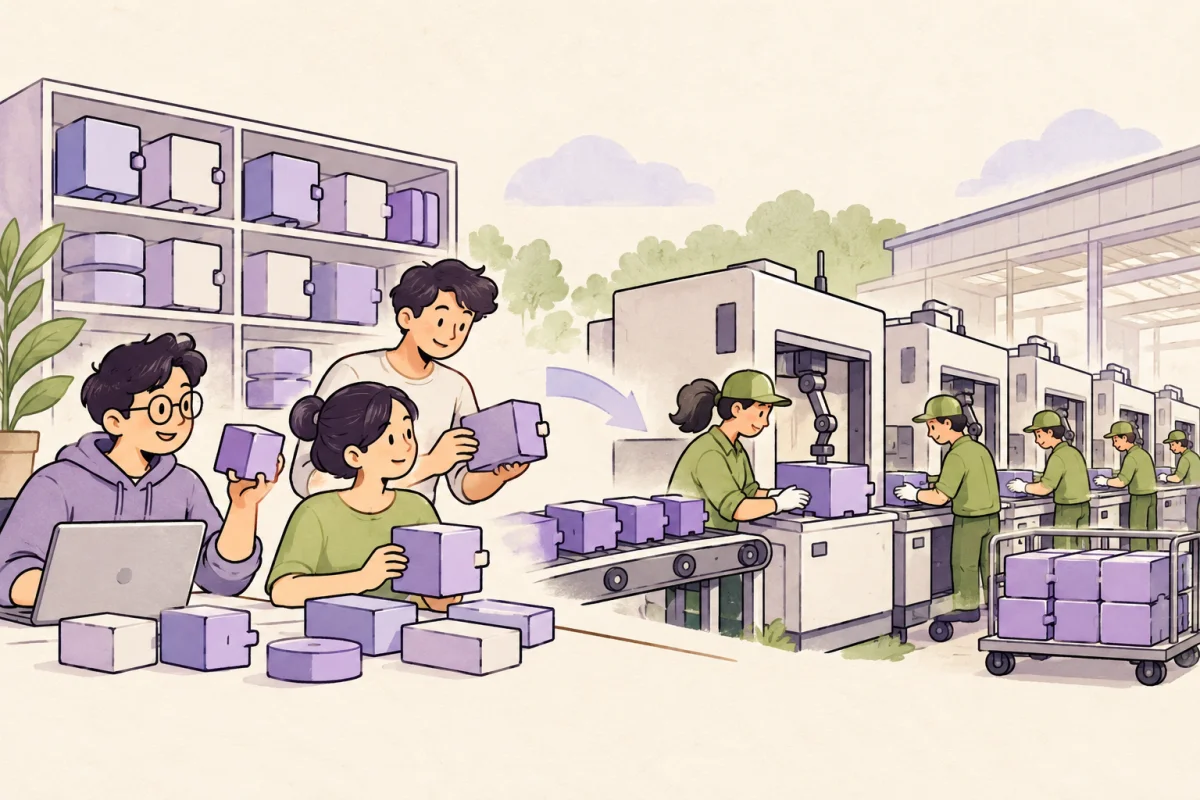
Adding developers while the number of reviewers stays the same is production under a short-run constraint. Redesigning the team and adding reviewers, test systems, and tools together opens a question about long-run scale. In manufacturing, adding people to the same machine differs from adding machines, space, supervisors, and quality systems together.
If every input rises, how much does output rise?
Returns to scale compare a proportional increase in all production inputs with the resulting increase in output, assuming unchanged technology. If all inputs rise 10% and output rises 12%, returns to scale are increasing. A 10% output increase means constant returns; 8% means decreasing returns.
This is a model for asking questions, not a promise that a 10% budget increase will yield any particular real output. Software jobs with different scopes need a comparable output unit. A manufacturer should compare good units meeting the same standard, rather than using all pieces to hide scrap.
Do not confuse this with diminishing marginal returns, which add one input while keeping others fixed. A new worker waiting longer for review does not prove that every larger business always has higher costs.
Unit cost may fall, if we count everything
Economies of scale mean long-run average cost falls as output expands. A business may specialize roles, share tools, or choose technology that pays off at greater volume. If coordination becomes so complex that average cost rises, diseconomies of scale may result.
Returns to scale describe inputs in relation to output. Economies of scale describe cost in relation to output, so input prices and technology choices matter too. Dividing the old rent bill by more jobs is not enough to establish long-run economies of scale.
An SI team or Odoo Partner may reuse test suites and data-migration methods, but it still needs to check usage rights, adapt them to customers, and maintain them as systems change. A manufacturer may combine purchasing or share specialized tools, but must also count freight, inventory, and quality checks.
Hypothetical case: When does reusable work pay off?
Suppose a team builds similar data integrations. Doing each project separately has relevant cost of THB 60,000 per project. Another option is a shared component costing THB 180,000 to build, followed by THB 30,000 per project for adaptation and testing. Both choices must deliver "the same quality and scope"
The difference per project is THB 60,000 less THB 30,000, or THB 30,000. Six projects: that is the number needed to recover the shared-component investment under these assumptions. At four projects, separate work costs THB 240,000 and the shared approach THB 300,000. At eight, the figures are THB 480,000 and THB 420,000, respectively.
The cost-equality point does not prove that investing now is wise. Recalculate if the projects are unconfirmed, scope changes, or the component requires additional maintenance. Expert time spent building it may displace other work. Do not double-count opportunity cost if it is already in relevant cost.
Manufacturing must compare making and buying on the same terms
Suppose manufacturing needs 1,000 good units per month. In-house production has THB 20,000 in avoidable fixed cost each month and THB 50 variable cost per unit, totaling THB 70,000. Outsourcing costs THB 75 per unit including freight and inspection, or THB 75,000. Making is THB 5,000 cheaper in this case.
At 500 units, making costs THB 45,000 while buying costs THB 37,500, reversing the result. Costs are equal at THB 20,000 divided by the THB 25 per-unit difference, or 800 units per month, provided unit costs and capacity stay within the assumed range.
If the THB 20,000 must still be paid after production stops, it is not a cost saved by outsourcing and the comparison must change. A machine already purchased may have resale value or another use. A new machine investment lasting years also needs cash-flow timing and the time value of money. This monthly example cannot replace a long-run investment appraisal.
Expand the parts that actually improve delivery
Before expanding, specify the output unit, quality, confirmed volume, and how long that capacity must be maintained. Record coordination, waiting, rework, and shared-component maintenance separately from active production time. That shows which constraint the extra spending is meant to relieve.
I would test with a small group of jobs before buying the full planned capacity against unconfirmed sales. If the volume does not arrive, the business still bears the cost of the scale it chose. Outsourcing also needs an owner for quality, data, and delivery; those costs do not vanish from the table.
The next table helps identify conditions to check before changing the size of a business.
| Question | Software / SI / Odoo team | Manufacturing |
|---|---|---|
| Comparable unit | Jobs with similar scope and acceptance criteria | Units meeting the same quality standard |
| Volume to support | Confirmed projects and delivery periods | Orders and month-to-month consistency |
| Costs easily missed | Adaptation, testing, maintenance, and coordination across teams | Setup, inspection, scrap, freight, and storage |
| Options before expansion | Improve the process, reuse work, or outsource a specific part | Resequence work, outsource production, or trial a tool |
| Triggers for review | Less reuse than expected or more rework | Lower volume, poorer quality, or late delivery |
Common questions
If more people still cannot keep up, is that a diseconomy of scale?
Not yet established. If review capacity or a tool is still fixed, this may be a short-run constraint. Examine changes to all inputs and long-run average cost before attributing the problem to scale.
Should we invest as soon as the costs are equal?
Check how certain volume is, delivery capacity, quality, cash needs, and any uncounted cost. Equality under one set of assumptions does not certify that every case is worthwhile.
Concept sources
This article draws on short- and long-run production, returns to scale, and long-run cost. The software, SI, Odoo Partner, and manufacturing cases are hypothetical applications I use to show how those ideas can inform business decisions.