Picture a freelance photographer in this hypothetical story. They do good work, clients return, and their calendar still has bookings. Yet when a new project comes in, the first question is when the payment will arrive.
The work and the fee still matter. Waiting to be paid has simply become harder. Equipment installments and studio rent are coming due. A job the photographer wants may pay slowly, while a less appealing one can pay sooner.
Judging by the work, this photographer is still good at their profession. In everyday life, though, there is less room to choose. The constraint is: the cash available at each point in time does not cover the obligations coming due
The work is delivered, but payment is still pending
The photographer handles everything from preparing the location and taking the photos to editing and delivering the files. Some clients pay after accepting the work. That leaves a period when the job is done but the fee has not arrived, while expenses for the next job may already have begun.
Some equipment was bought on installments. There were reasons for the purchase at the time: the quality of the work and the jobs the photographer expected to take. Financial obligations do not always begin with careless spending. In this hypothetical case, the problem arises when incoming cash is delayed while several payment deadlines stay put.
With enough accessible cash, the wait might be an inconvenience. When most cash is already set aside for existing obligations, a single late-paying client can force someone to find another job quickly. A freelancer then schedules work around payment dates as well as project deadlines.
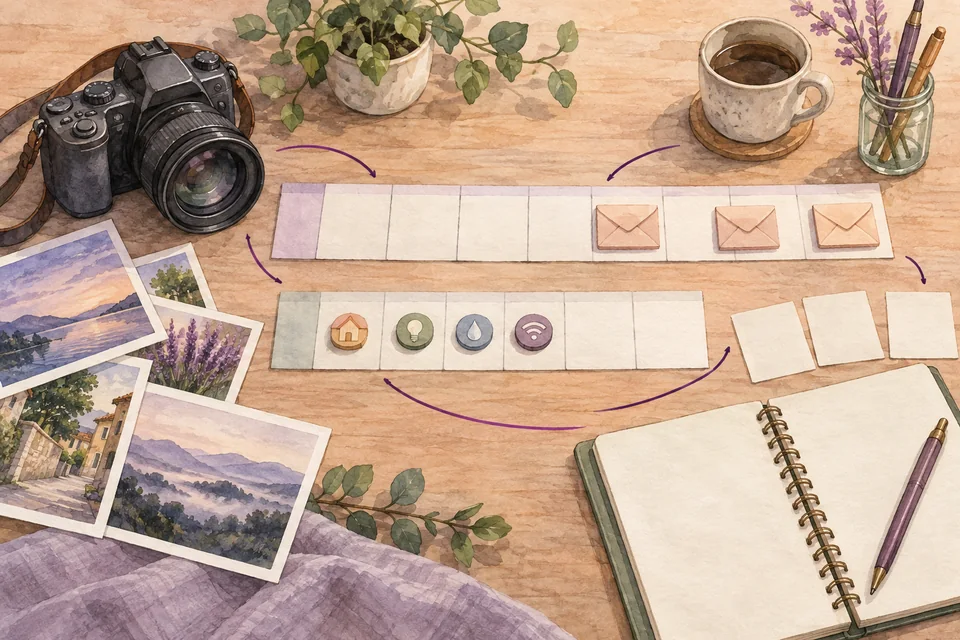
Payment for the hypothetical job
- Deliver work
- Wait for acceptance
- Receive payment
Bills due in the meantime
- Equipment installments
- Studio rent
- Essential expenses
Conceptual diagram based on a hypothetical story, with no time scale. Payment terms and due dates differ from person to person.
When waiting is impossible, there is less room to negotiate
Suppose an urgent job comes in. The fee is lower than the photographer hoped, and the deadline cuts into time meant for rest or preparation for an existing job. If they could wait for another offer, they might negotiate or decline. This time, the client can pay before a bill comes due, so they accept.
Accepting may be necessary at that moment. It should not become a reason for outsiders to judge the person doing the work. Someone who seems to agree to everything may be trying to cover essential expenses. The job may genuinely solve an immediate problem, without making all the obligations that follow disappear.
If the pattern continues, there may be less time to find new kinds of clients, improve the way the work is done, or learn something they want to do next. Creating new options takes time, but that time has already been traded for urgently needed cash. A portfolio or work history may not show this constraint to anyone looking in from outside.
To me, part of financial freedom lies here: how much room do we have to wait, decide, and negotiate? High income in some months does not fully answer that. After scheduled obligations are paid, what money and time remain for real choices?
Financial obligations do not erase someone's ability
This story should not end with a simple judgment that the photographer planned badly. Income can vary, payment terms can change, and people's essential expenses differ. Knowing how to do good work does not give us control over all of those things.
Some debt pays for the tools of a trade or helps someone through a necessity. The useful questions are whether those obligations fit the income that can realistically arrive and what happens if that income is late. Labeling everyone with debt as irresponsible obscures the problem that actually needs attention.
At the same time, it matters to acknowledge when obligations are limiting rest and the choice of work. The photographer in this story is still skilled, still cares for the quality of the work, and still has things they want to do. Seeing the cash constraint helps identify which obligations or payment dates need attention, without concluding that the person has lost their worth.
Gradually make more room to choose
If I were beginning to address this situation, I would first list which payments are expected and when, alongside every bill due before them. Total income alone can hide a period when cash runs short. Recording the dates reveals where the waits are and whether obligations exceed what the expected receipts can support.
What can change depends on the work and each person's terms. A photographer might try to agree on a deposit or payments at project milestones, where the agreement allows it. Someone else may need to avoid taking on new obligations first. If scheduled debt payments have become unmanageable, contacting the creditor, explaining the situation, and discussing terms is another option to consider. The outcome depends on the discussion and the creditor's assessment; relief is not guaranteed.
If money can gradually be set aside, a reserve may make it less necessary to accept every offer just because cash will run out before the next fee arrives. Telling someone to save immediately can be unrealistic when income does not yet cover essentials. Sometimes the first possible steps are to see the position clearly, find someone who can help assess the options, and avoid adding obligations in the hope that things will improve on their own.
For the photographer in this story, the first goal may be smaller than a life free of money worries. The first step: having time to think before accepting a job, or being able to decline terms they cannot sustain restores some choice. Their skills can then be used more often on work chosen for their own reasons.
Further reading on managing money
The photographer is fictional. For basic guidance on income, expenses, and discussing debt payments when they become unaffordable, see the Bank of Thailand's budget planning and debt payment guidance.