The cover depicts a hypothetical situation. It does not show an actual audit or establish the qualifications of anyone pictured.
The inventory total in the enterprise resource planning system (ERP) matches the trial balance, but a count in the warehouse does not. A business owner may ask, "Can the auditor sign off anyway?" I would step back one question: What evidence supports the figures on which the auditor is being asked to give an opinion, and how much does the difference affect the financial statements?
A Thai CPA is a licensed certified public accountant. The license must be issued by the Federation of Accounting Professions under the applicable requirements. Graduating in accounting or passing exams alone does not make someone a license holder. A license does not replace proper acceptance of an engagement, independence, or additional regulator requirements for particular work. [Accounting Professions Act B.E. 2547 (2004)]
This is the second article in the series "What CIA, CPA, and CFA Prepare You to Do." Here, CPA refers to the Thai qualification. Requirements and authority in other countries may differ. The CIA discussed in the first article is an internal audit certification and does not replace this license.
What does an auditor's report tell us?
An audit aims to obtain reasonable assurance that the financial statements as a whole are free from material misstatement, whether caused by fraud or error. "Reasonable" means a high level of assurance, not an absolute guarantee that every problem has been found. [Thai Standard on Auditing 200]
The auditor uses evidence to form an opinion on financial statements under the financial reporting framework applicable to the business. A signature at the end of the report should not be read as "this company has no fraud," "every item of inventory was counted," or "this business will have no future problems." Read the wording of the opinion, the scope, and the disclosures in the statements together. [Thai Standard on Auditing 700]
From the ERP balance to warehouse evidence
Take the same hypothetical parts manufacturer. At period-end, the accounting team finds a difference between inventory records and the physical count. Some goods have not yet been received, and others have not moved for a long time. Management needs to investigate the causes, assess values, and prepare support for the statements. Sending the auditor only a file of totals and waiting for a report is not enough.
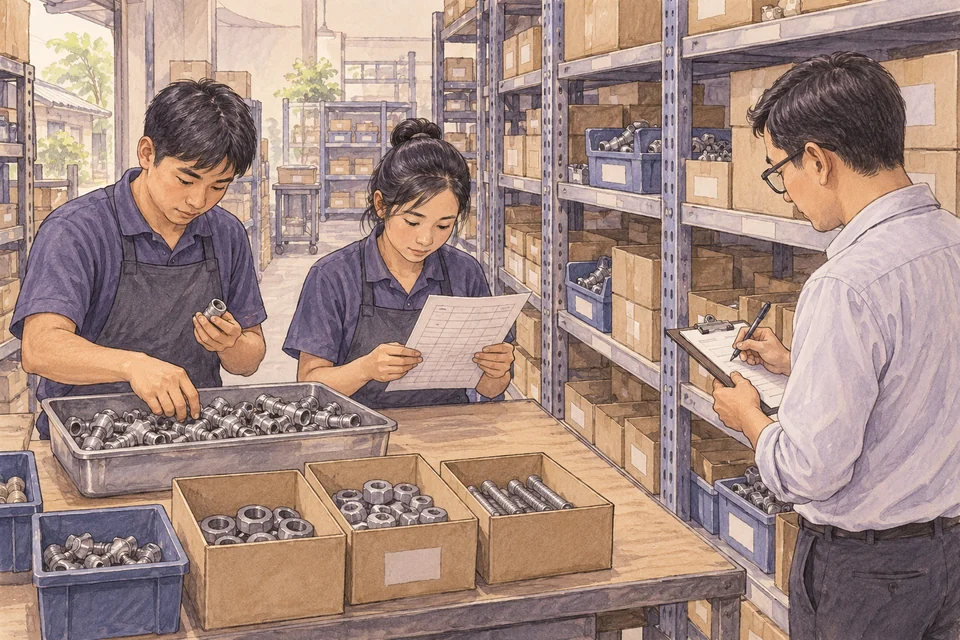
The auditor may need to understand the count process, inspect evidence about inventory quantities and condition, and consider receipts and dispatches close to period-end and how inventory is valued. Actual procedures depend on the engagement's risks and circumstances. ERP data is part of the evidence, but the system itself does not make a balance correct.
Overdue receivables raise a similar issue. Invoice totals may match the accounts, yet recognition and measurement still need assessment. Have customers paid since period-end? Are any amounts disputed? Adjustments and disclosures are management's responsibility. The auditor independently evaluates the evidence and what it means for the audit.
| Role | Responsibility | What the role does not imply |
|---|---|---|
| Management | Prepares the financial statements and necessary internal controls, and provides information relevant to the audit | Hiring an auditor does not transfer responsibility for preparing the statements away from the business. |
| Accountants and systems team | Record, reconcile, and provide information within their roles, and maintain systems that support the work | Keeping books or implementing an ERP does not automatically grant authority to sign as the auditor. |
| Auditor | Audits under the standards, obtains sufficient appropriate evidence, and expresses an opinion on the financial statements | The opinion does not guarantee every transaction or the business's survival. |
If the same service provider helps implement the system and proposes to perform the audit, independence and ethics requirements must be assessed before accepting the engagement. Knowing the client's data well does not remove the risk of reviewing one's own work.
The Thai CPA path has several separate requirements
Prospective applicants should first check whether the Federation of Accounting Professions recognizes their accounting degree and curriculum, as well as the membership requirements. Do not assume that any bachelor's degree or an MBA satisfies them all. The conditions for registering as an audit trainee and sitting each exam subject need separate review.
While preparing
Check qualifications, register for audit training, and plan exams according to your eligibility. Some steps can take place during the same period.
When requirements are complete
Apply for a license through the Federation's process. Passing the exams does not automatically issue a license.
The ordinary practical-training route requires at least three years and 3,000 hours within five years of applying for trainee registration. Both the period and the hours must be met, with reports and supervisor verification submitted as required. Register properly before counting the work; do not collect hours retrospectively and assume they all qualify. [Audit practical-training handbook]
The current exam has six subjects: Accounting 1 and 2, Auditing 1 and 2, and Laws Related to the Auditing Profession 1 and 2. Eligibility to take each subject still depends on the subject's conditions and the applicant's qualifications. [Federation's 2026 examination announcement]
A passing result for each subject may be carried forward for no more than seven years from the date that subject was passed, under criteria amended in 2024. The older four-year rule may still appear in older articles. Check your own results in the system and the announcement governing the actual application period. [Online services and examination criteria]
Check individual degree eligibility, approved training alternatives, and application documents directly with the Federation. This article sets out the main path to show that knowledge, experience, exams, and the license are separate requirements.
Holding a license also means maintaining standing
The law does not set an ordinary fixed expiration period for the license. Holders still have to maintain their qualifications and meet membership, fee, ethics, and continuing professional development duties. Obtaining the license once does not mean there is nothing more to do.
The current continuing professional development (CPD) requirement totals 40 hours a year: 20 formal and 20 informal hours. The formal portion includes minimum accounting or auditing and ethics components. The first year and the way hours are counted have specific conditions, so check the service page when planning your own compliance. [Federation's CPD guidance]
What should a business owner prepare to keep the audit moving?
I would start by aligning on the scope, delivery dates, and the team's readiness. Then I would assign an owner for each set of information: the general ledger, inventory reports, reconciliations, and evidence for significant transactions. Where figures differ, keep the cause, the correction, and supporting records. Do not erase the trail of an earlier entry simply to make two totals agree.
When the auditor asks for more information or proposes an adjustment, discuss which fact or reporting question is being addressed and what management must decide. If evidence is limited, discuss the effect on the audit and its report. Do not pressure the auditor to sign merely to meet a filing date. License status can be checked through the licensed CPA lookup.
If you need an auditor's report, start with the audit work to be done and the evidence to prepare. Then check the proposed auditor's authority and suitability. Asking for a "CPA signature" without those conversations skips the heart of an audit.
Official sources were checked on October 18, 2026. The factory and inventory problem are hypothetical, not findings about a client or an opinion on any financial statements. Businesses and engagements subject to specific regulation may have further requirements.